Mortgage Rate Primer
Tips & Advice
Tips & Advice
One of comments I hear a lot from the public is “The Fed lowered mortgage rates so the market should be better”. At the risk of wading into economics, a subject most people find about as interesting as watching paint dry, it is important to clarify how mortgage rates work.
Simply put… the Federal Government does not control mortgage rates. However, the Federal Reserve (“the Fed”) does set the Federal Funds Rate, which is a bell weather rate that banks charge to lend funds to other banks on an overnight basis. This interest rate influences short term rates such as the prime rate, as well as consumer loans and credit cards. More importantly, it signals the Fed’s outlook on the economy and inflation, and impacts the broader investment environment.
The Fed acts as the driver of the economy, using monetary policy as a gas pedal or break depending on conditions. They accomplish this by lowering or raising the Federal Funds rate. When the economy is slowing, the fed can lower the Federal Funds rate to stimulate the economy. When the economy is too robust or inflation is higher than their target, they can raise the Federal Funds rate to slow economic growth and (hopefully) tame inflation.
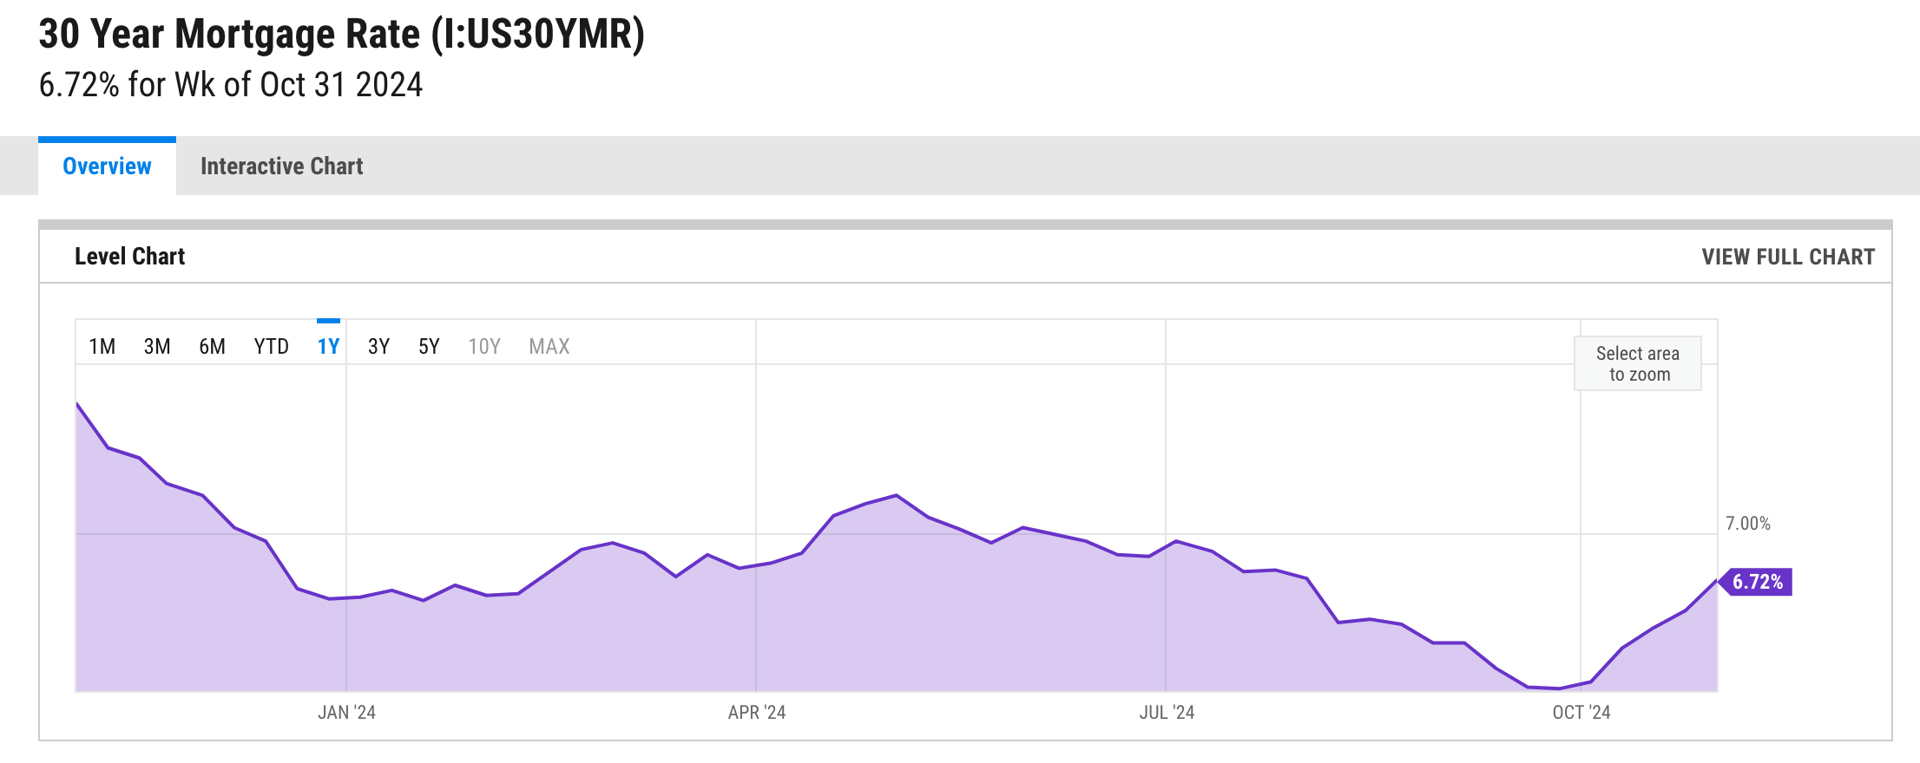
The mortgage market is not controlled by the Fed, but rather is essentially a bond market driven by investors and the rate of return (interest rate) they are willing to accept when taking into account inflation and the long-term economic outlook. Mortgage rates most closely track the 10 year Treasury market. As we have seen, even though the Fed recently lowered the Federal Funds Rate, average mortgage rates have risen by about .75% since the beginning of October. How can this be?
One word… inflation. The answer is investors are simply not convinced inflation will hit the Fed’s target rate of 2%, so they will demand a higher rate of return to offset the effects of higher inflation. If investors think that lowering the Federal Funds Rate will fuel more inflation, they will demand higher returns in the form of higher interest rates.
Stay up to date on the latest real estate trends.
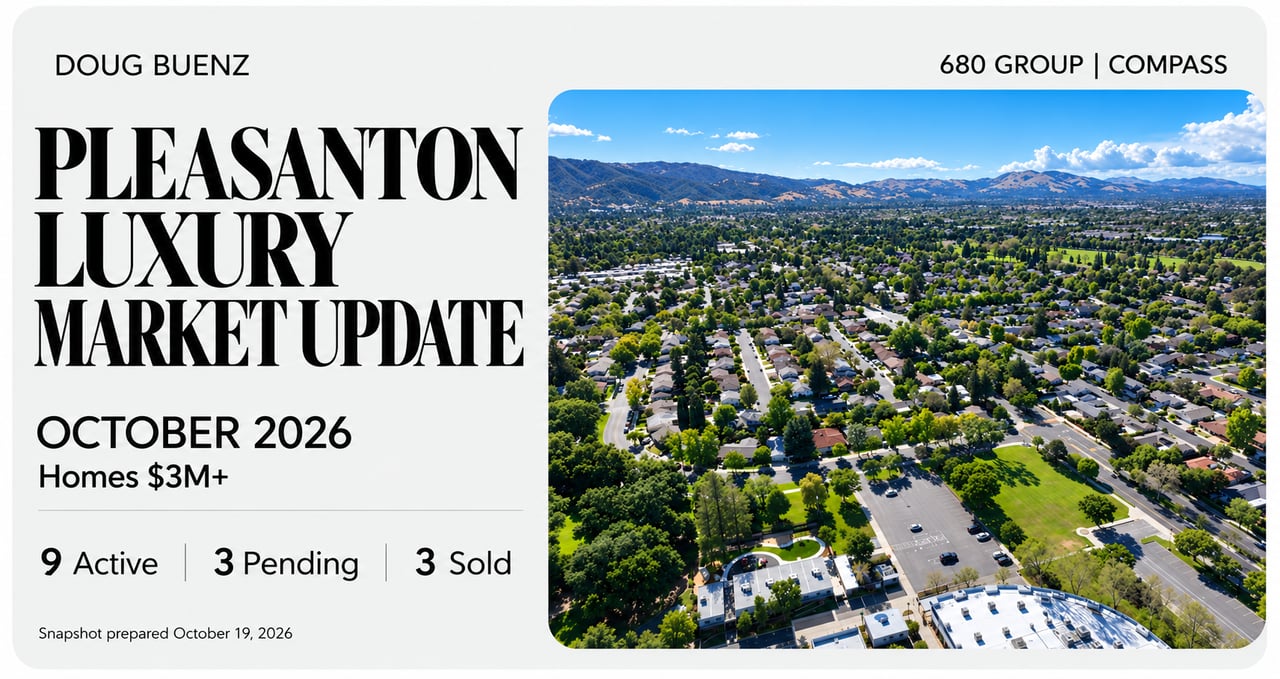
Pleasanton luxury real estate
Doug Buenz | October 23, 2026
Two distinct markets: Limited inventory below $4 million, more choices at higher prices, and why strategic pricing matters.
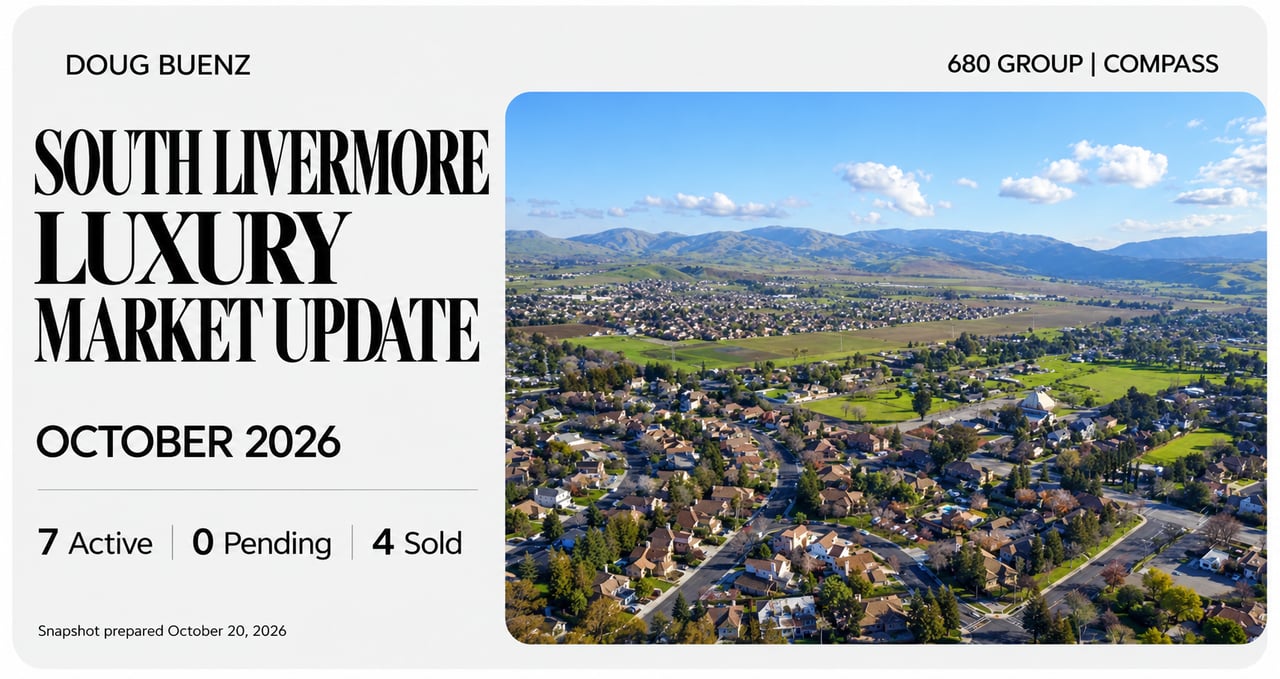
South Livermore
Doug Buenz | October 22, 2026
Seven luxury homes are on the market in South Livermore, with no pending sales. Four closings show how time on market relates to sale-to-list results.
Tri-Valley real estate
Doug Buenz | October 21, 2026
Seventeen active listings and five closings highlight the importance of property specific pricing
Market Update
Doug Buenz | October 16, 2026
Inventory has leveled off, buyer activity has slowed, and accurate pricing is becoming increasingly important.
Market Update
Doug Buenz | October 12, 2026
Inventory has leveled off, buyer activity has slowed, and strategic pricing continues to shape results.
Market Update
Doug Buenz | October 9, 2026
Well-priced homes are selling quickly, while longer market times give buyers more negotiating room.
Market Update
Doug Buenz | September 21, 2026
Inventory remains elevated, absorption stays below 40%, and Dublin buyers are separating well-positioned homes from listings that miss the market.
Market Update
Doug Buenz | September 19, 2026
Pricing Precision Shapes the Early Fall Market
Market Update
Doug Buenz | September 15, 2026
August 2026 single-family home data for Pleasanton, California, published September 2026